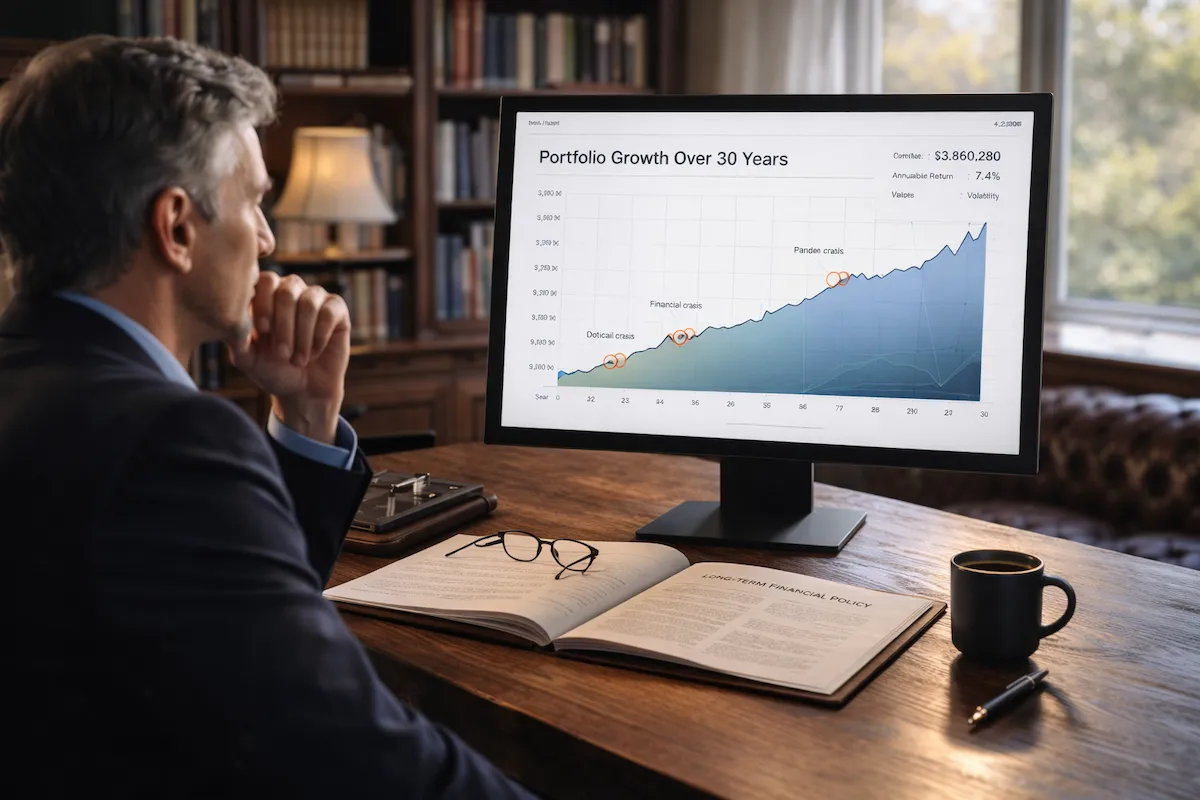
An investment strategy is only as good as its weakest moment. In the world of finance, sustainability isn't about the highest annual return; it’s about the strategy's ability to remain intact through every economic season.
In 2026, the markets are faster and more reactive than ever. Many investors start with complex plans that look perfect on a spreadsheet but crumble when faced with real-world volatility or personal lifestyle changes. A sustainable strategy is one that balances your financial goals with your human reality, ensuring that you don't abandon your plan when it matters most. Following our deep dive into global diversification, we now look at the glue that holds those assets together. In this guide, we will analyze the structural pillars of investment longevity: cost efficiency, tax optimization, and the psychological "buy-in" required to stay the course for thirty years or more.Structural Integrity Through Low Friction
The primary enemy of a sustainable strategy is "friction"—the combination of high management fees, excessive trading costs, and emotional interference. Over a 30-year horizon, even a 1.5% difference in annual fees can reduce your final portfolio value by hundreds of thousands of dollars. To ensure sustainability in 2026, professional strategists prioritize low-cost index funds and ETFs as the "Core" of the portfolio. By minimizing the amount of money leaking out to intermediaries, you maximize the power of compounding interest, which is the engine of long-term wealth. [Image: A realistic photo of a digital tablet displaying a bar chart comparing portfolio growth with 0.5% fees vs 2.0% fees over 30 years.]The Role of Systematic Rebalancing
Markets are dynamic; some sectors grow faster than others, causing your portfolio to drift away from its intended risk level. A sustainable strategy includes a pre-set mechanism for Rebalancing. This is the disciplined act of selling high-performing assets and buying underperforming ones to return to your original target.The Rebalancing Logic
In 2026, most sustainable plans use one of two triggers:- Calendar Rebalancing: Reviewing and adjusting the portfolio every six or twelve months.
- Threshold Rebalancing: Adjusting only when an asset class moves more than 5% away from its target weight.
Adaptability to Life Stages
A strategy that works for a 25-year-old is rarely sustainable for a 55-year-old. Sustainability requires Life-Cycle Awareness. As you move closer to your goals, your strategy must transition from aggressive wealth accumulation to wealth preservation and income generation.| Phase | Strategic Focus | Sustainability Factor |
|---|---|---|
| Accumulation | High Growth | Maximizing contributions and time. |
| Consolidation | Balanced Risk | Reducing volatility while maintaining growth. |
| Distribution | Income/Safety | Ensuring withdrawals don't deplete principal. |
💡 Pro-Tip: Tax-Loss Harvesting Sustainability is also about tax efficiency. In 2026, sophisticated investors use "Tax-Loss Harvesting"—selling losing positions to offset capital gains taxes. This reduces your "Tax Friction" and keeps more capital working for you in the market.